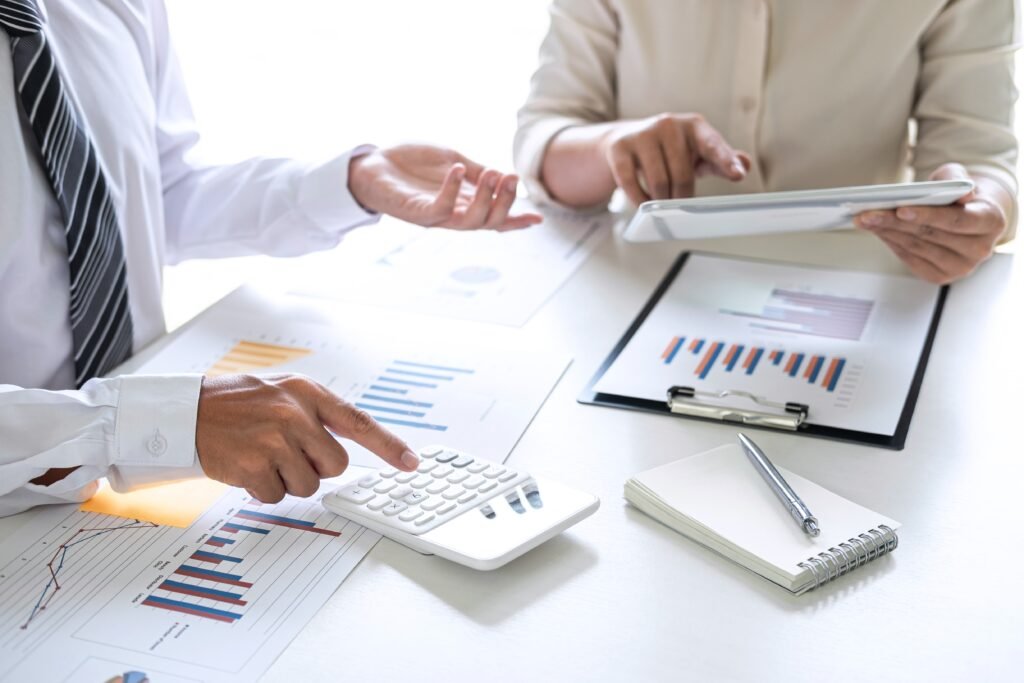
Group of Business leader team conference on meeting presentation to planning investment project working and strategy of business making conversation with partner, financial and accounting concept.
Achieving long-term financial stability requires more than simply saving money; it demands a structured, strategic approach to managing your wealth. Whether your goal is buying a home, funding higher education, or securing a comfortable retirement, robust financial planning techniques serve as the roadmap to turning your ambitions into reality. By taking control of your assets, optimizing tax efficiency, and minimizing potential risks, you can build a resilient foundation capable of withstanding economic uncertainty.
Establishing Clear and Measurable Financial Objectives
The first step in any effective financial strategy is identifying what you want to accomplish. Vague intentions like “saving more money” rarely lead to actionable results. Instead, frame your goals using specific timelines and monetary targets.
- Short-Term Goals: Focus on objectives reachable within one to three years, such as establishing an emergency reserve, paying off high-interest debt, or funding an upcoming vacation.
- Medium-Term Objectives: Target achievements expected in three to seven years, including saving for a home down payment or starting a new business venture.
- Long-Term Ambitions: Look toward milestones five to ten-plus years away, primarily focused on retirement planning, estate planning, and wealth transfer.
By categorizing your goals by timeframe, you can assign appropriate investment vehicles to each, matching risk levels to your required liquidity.
Mastering Cash Flow and Budgeting
A solid financial foundation relies entirely on understanding your cash flow—the balance between income and expenses. Unmanaged cash flow often leads to silent wealth erosion through lifestyle inflation and unnecessary spending.
Tracking Income and Expenditures
Begin by logging every stream of income alongside recurring monthly liabilities. Categorize expenses into fixed costs (rent, utilities, insurance) and variable costs (dining, entertainment, subscription services). Knowing exactly where your money goes highlights areas where small adjustments yield significant savings over time.
Choosing the Right Budgeting Framework
Several proven budgeting frameworks exist to keep spending aligned with financial objectives:
- The 50/30/20 Rule: Allocate 50% of net income to needs, 30% to wants, and 20% to savings and debt reduction.
- Zero-Based Budgeting: Assign every dollar a explicit job before the month starts, leaving zero unallocated funds.
- Pay Yourself First: Automatically divert a set portion of your income into savings or investment accounts immediately upon receiving your paycheck, living on the remainder.
Building an Unshakable Emergency Reserve
Unforeseen challenges—such as medical emergencies, job disruptions, or urgent home repairs—can derail even the most carefully constructed financial plan if you are unprepared. An emergency fund acts as a financial shock absorber, preventing you from resorting to high-interest debt or liquidating long-term investments during market downturns.
Aim to save between three to six months’ worth of essential living expenses in a highly liquid, low-risk account, such as a high-yield savings account. Keep these funds distinct from your day-to-day checking account to reduce the temptation to spend them on non-essentials.
Smart Debt Management and Elimination
Not all debt is created equal, but high-interest debt—particularly credit card balances—is one of the greatest obstacles to building lasting wealth. Prioritizing structured debt repayment unleashes cash flow that can be redirected toward wealth accumulation.
Effective Debt Repayment Strategies
Two widely accepted strategies can help structure your debt payoff plan:
- The Debt Avalanche: Pay minimum balances on all debts while directing extra cash to the liability with the highest interest rate. Mathematically, this saves the most money in interest charges over time.
- The Debt Snowball: Pay minimums on all obligations while directing extra cash toward the smallest balance first. The quick win provides psychological momentum to sustain momentum over time.
Developing a Strategic Investment Plan
Saving money is essential, but cash held idle in standard accounts loses purchasing power to inflation over time. Wealth building requires investing in assets that grow faster than the rate of inflation.
Wealth Building through Asset Allocation
A well-balanced investment portfolio balances growth against risk exposure. Diversifying investments across major asset classes—such as equities, fixed income, real estate, and cash equivalents—ensures your portfolio isn’t overly vulnerable to any single market decline.
When seeking guidance on structuring a resilient portfolio, reviewing insights from established industry professionals can offer valuable perspective. For instance, exploring Ed Rempel reviews highlights how specialized financial advice, tax-efficient strategies, and disciplined long-term portfolio management help investors navigate market cycles while remaining focused on cash-flow-driven independence.
Maximizing Tax Efficiency
Tax efficiency plays a pivotal role in long-term wealth preservation. Lowering your tax burden allows a greater portion of your earnings to compound over time.
- Tax-Advantaged Accounts: Take full advantage of registered retirement accounts, pension plans, or employer-sponsored savings vehicles. These accounts offer tax-deductible contributions, tax-deferred growth, or tax-free withdrawals depending on their structure.
- Strategic Asset Location: Place investments that generate income subject to higher tax rates inside tax-sheltered accounts, while holding tax-efficient assets in taxable margin or brokerage accounts.
- Tax-Loss Harvesting: Periodically offset capital gains taxes by strategically selling investments that have lost value.
Comprehensive Risk Management and Insurance
Protecting your accumulated wealth is just as critical as growing it. A single catastrophic event can erase years of progress without adequate risk mitigation strategies.
Evaluate your coverage across essential categories:
- Life Insurance: Ensures financial continuity for dependents in the event of income loss.
- Disability Insurance: Protects your earned income stream if illness or injury leaves you unable to work.
- Health and Property Insurance: Safeguards against severe medical bills, liability claims, or property destruction.
Regularly review policy terms and coverage limits to align insurance protections with your evolving asset level and life stage.
Long-Term Estate and Legacy Planning
Financial stability extends beyond your own lifetime. Proper estate planning ensures that your accumulated assets pass smoothly to designated beneficiaries with minimal friction, legal costs, and tax penalties.
Key elements of a comprehensive estate plan include:
- Drafting a legally binding will to detail asset distribution.
- Setting up powers of attorney for financial and medical decision-making in the event of incapacity.
- Utilizing trusts where appropriate to streamline asset transfers and shield inheritances.
- Keeping beneficiary designations current across bank accounts, retirement plans, and insurance policies.
Maintaining Flexibility Through Periodic Reviews
Financial planning is not a one-time event; it is an ongoing process. Economic conditions change, investment markets shift, and personal milestones—like marriage, career changes, or retirement—demand adjustments.
Schedule financial reviews at least once or twice annually to evaluate your progress. Assess whether your current portfolio balance matches your target risk exposure, adjust budgets for major life updates, and refine your goals to stay aligned with your long-term vision.
By combining disciplined budgeting, smart debt reduction, risk management, and tax-efficient investing, you establish a complete framework that safeguards your present well-being while compounding your wealth for the future.
More Stories
Financial Planning Checklist for a More Secure Financial Life
What Are Interim CFO Services for Companies?
Professional Bookkeepers & Fractional CFO Services: The Smart Finance Solution for Modern Companies